
Skip to content
SuperSeed Accelerator LogoSuperSeed Accelerator Logo
  • Portfolio
  • Team
  • Careers
  • Journal
  • Contact
Submit

Why are early-stage valuations going up?

Despite the macroeconomic backdrop, seed valuations have gone up in 2022. What's happening?

19.12.2022

Saas
Valuation
Venture-capital

Mads Jensen
Managing Partner​

"Nothing is more powerful than an idea whose time has come. Especially when it's championed by world-class founders!"

Mads Jensen

Managing Partner​

Mads is a successful entrepreneur and passionate technologist (having authored multiple US patents) who has worked for 2 decades building and growing tech businesses. At SuperSeed he helps ambitious technical founders build great companies from the early stages. Prior to SuperSeed, Mads was an entrepreneur, taking Sefaira (a SaaS company) from inception in 2009 to exit in 2016. Before that he was a business executive at IBM.

Why are early-stage valuations going up?
Share
TL;DR

Writing in December 2022, Mads Jensen explains that rising US seed valuations reflected a flight to quality, with fewer, bigger firms backing only the best companies, while stable European round sizes amid falling deal volumes amounted to a relative price cut.

Key Takeaways
  • Growth-stage valuations collapsed in 2022; Klarna raised at an 85% lower price than its 2021 valuation.
  • Pitchbook's 2023 US Venture Capital Outlook showed US seed valuations rising in 2022.
  • Only the best companies were getting funded, and they raise more than the median, pushing up median valuations and round sizes, helped by large firms such as Accel, Andreessen, Lightspeed and Sequoia doing more seed deals.
  • Dealroom data showed typical European seed rounds of about $2.2m and Series A rounds of about $7.9m stable from Q4 2021 to Q3 2022, while deal volumes fell 20%.
  • Higher-quality deals at the same price meant a relative price cut in Europe, so the reality was more mixed than headline valuations suggested.

Why are early-stage valuations going up?

Growth stage valuations have collapsed this year. Like public market tech investors, private growth-stage investors have taken a bath. Earlier this year, Klarna raised money at an 85% lower price than its 2021 valuation. Ouch.

But what’s going on at the early stages?

On Friday, Pitchbook released the 2023 US Venture Capital Outlook. Far from decreasing, it shows US Seed valuations going up in 2022.
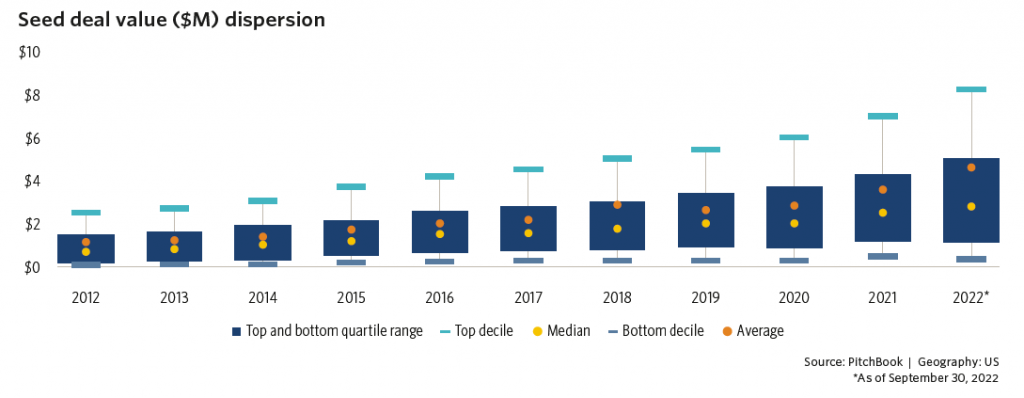
Pitchbook analysis – US Seed Valuations going up in 2022

Given the macroeconomic backdrop, this seems counterintuitive.

But there is a simple explanation. The main driver has been a flight to quality:

  • the bar has gone up. Fewer deals are getting done, and only the best companies are getting funded.
  • the best companies, on average, raise more money than the median performer.
  • as only the best companies are raising, the median US valuation and round size is going up.
  • this is further compounded by the bigger firms doing more seed deals. Accel, Andreessen, Lightspeed, Sequoia etc have been more active in US Seed in 2022. And they tend to write bigger cheques.

So fewer and bigger firms writing fewer and bigger cheques. That’s the story of US venture capital so far in 2022.

How are things looking in Europe?

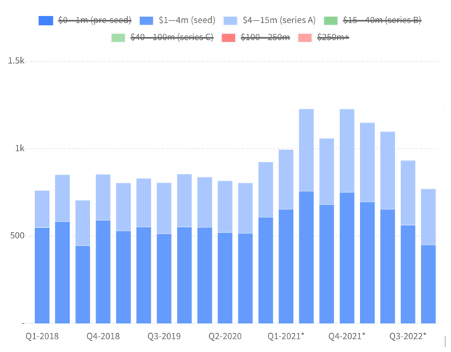
According to Dealroom data, European Seed and Series A round sizes were stable between Q4 ’21 and Q3 ’22. ~$2.2m for the typical Seed and ~$7.9m for the typical Series A.

But volumes are off by 20%, down from 1,150 investments in Q4 of last year to 934 in Q3 of this year. The expectation is that the number will decline further in Q4. Even adjusting for the usual lag in the data, the data matches what we see on the ground. Fewer deals are getting done.
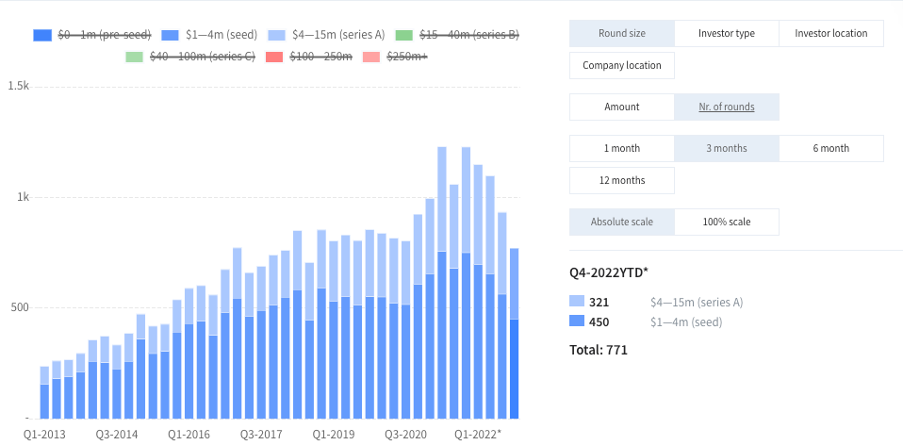
Let’s assume a similar pattern to the US – i.e. that only the best investments get made. This means that the average investment in Q3 of this year was into a higher-quality opportunity (traction, risk, team etc). And if the average investment is of higher quality, and the average price is the same – well – that’s a relative price cut.

So although it looks like valuations have continued to increase at the earliest stages, the reality on the ground is more mixed.

This is a tough time for founders. Most have had to adjust their plans in light of the funding market. But ultimately, we see much better businesses being built. More judicious spending and better unit economics. And I expect that the near-term pain felt by entrepreneurs will translate into better long-term outcomes for all.

Founders as well as investors.

Frequently Asked Questions

Why did seed valuations rise in 2022 while growth-stage valuations fell?

According to the post, because of a flight to quality: fewer deals were done, only the best companies were funded, those companies raise more than average, and large firms writing bigger cheques were more active at seed.

What happened to European early-stage rounds in 2022?

Dealroom data showed typical seed and Series A round sizes holding steady at about $2.2m and $7.9m, but the number of investments fell from 1,150 in Q4 2021 to 934 in Q3 2022.

Was the 2022 downturn bad for startups in the long run?

Mads Jensen acknowledged it was a tough time for founders, but expected the better businesses being built, with more judicious spending and better unit economics, to lead to better long-term outcomes for founders and investors.

Share

Related

Should You Buy Anthropic at $2 Trillion?
31.10.2026
The Second Half
30.09.2026
How Worried Should We Be About AI?
27.09.2026
The World Is Still Figuring Out How to Use AI
31.08.2026
Humanoids – The Newton or the iPhone?
31.07.2026

APPLY FOR FUNDING

Submit your investor deck
and get a response in minutes

Uploading your deck...

You'll be redirected to the application form in a moment.

Having trouble? Contact us.

SuperSeed Accelerator Logo
Privacy Policy
Close

Stay up to date via our newsletter

Sign up with your email address to receive news and updates.

SuperSeed Accelerator Logo
Company
  • Portfolio
  • Team
  • Careers
  • Journal
  • Contact
  • ESG
Investors
  • SuperSeed Capital
  • Fund Facts
  • Documents
  • Board of Directors
  • Media Kit
Get in touch
  • Apply for funding
  • Email
  • LinkedIn
Newsletter
By subscribing to our newsletter, you accept our Privacy Policy. Submit

CAPITAL AT RISK. Read more about the key risks of investing here.

Investing in early stage companies involves risks including loss of capital, illiquidity, lack of dividends and dilution. The availability of tax relief depends on individual investors' circumstances, and on investee companies' qualifying status, both of which may be subject to change. All contents ©2026 SuperSeed Ventures LLP registered in England and Wales under registration number OC424095. Our registered office is 27 Old Gloucester Street, London, WC1N 3AX and our principal place of business is at 231-232 Strand, London WC2R 1DA. SuperSeed Ventures LLP is Authorised and Regulated by the Financial Conduct Authority (FRN 920283)

© SuperSeed Ventures LLP 2026
Manage Cookie Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • Privacy Policy
  • {title}