


SuperSeed explains why B2B SaaS companies should report Committed MRR (CMRR) alongside MRR: MRR lags signed deals and announced churn by months, while CMRR shows the committed revenue position as soon as it changes.
- MRR is an accounting measure of recognised revenue, so churn and new deals signed today may not show up in reports for two or three months.
- CMRR is an operational metric showing the total pool of committed recurring revenue, and is often a better internal and board KPI.
- One way to calculate CMRR is to start with MRR, add signed upsells and new business not yet live, and subtract downgrades and churn the customer has communicated.
- Companies still need to track MRR for their accounts, so good practice is to report both.
- Implementation fees and other one-off revenue should be reported separately and not mixed into MRR.
B2B SaaS companies live and die by their ability to grow Monthly Recurring Revenue (MRR). From a valuation standpoint, highly profitable recurring revenue is the thing that sets them apart from so many other business models. High margin revenue that keeps rolling in every month, what’s not to like?
But it turns out that MRR isn’t always the best metric for keeping track of what’s happening with your business.
Imagine that one of your customers is telling you that they are not going to renew their contract. Now imagine that the last day of the contract is Dec 31st, and that the customer is worth 20% of the company’s MRR. When the company is reporting MRR for December, everything looks great. The recognised revenue doesn’t decline until January and won’t show up in reporting until a month later. But in fact, the company lost 20% of the MRR base in Q4 (assuming no new customers). That might have been helpful information to report.
Now consider the opposite example. Consider the same business signed new business in December that’s expanding MRR by 40%. But the new contracts aren’t starting until February 1st the following year. If we only look at reported MRR, December looks fine (flat month), January looks like a disaster (20% contraction), and February looks amazing — a 50% increase on January!
Numerical example below :
Previous run-rate: $100k MRR
Churn: $20k MRR (20% contraction)
Growth: $40k MRR (40% growth)
Jan MRR: $80k (20% down from Dec)
Feb MRR: $120k (50% up from Jan)
In this case, we’d report amazing progress in our February numbers. However, these aren’t reported until March, a full 3 months after the deals were done in December. Not a useful way to manage the business.
What’s the solution? Enter Committed MRR (CMRR)
Whereas MRR is an accounting term that reflects the revenue we recognise from delivering our contracts, CMRR is a business operations metric that shows the total pool of committed revenue we have attained. As an internal and board KPI, it is often a much better metric than MRR. This doesn’t mean that we shouldn’t track MRR (we have to — otherwise, we can’t do our accounts), but it’s good practice to report both.
CMRR in practice
So how do we calculate CMRR? It’s not a formal accounting term, and there is more than one way to calculate the figure. One way is as follows:
- Start with your MRR
- Add upsells and new business that has been signed by your customer, but which doesn’t yet figure in your MRR. Example: Sign contract in December for a start on Feb 1st. The December MRR does not include these numbers, but the December 31st CMRR does include them.
- Subtract downgrades and churn that have been communicated by the customer, but which hasn’t yet been included in your MRR. Example: Contract expires in December. The customer didn’t sign by December 31st. When you do your reporting in the first week of Jan, you know that the contract churned, so you subtract that MRR from the December CMRR number.
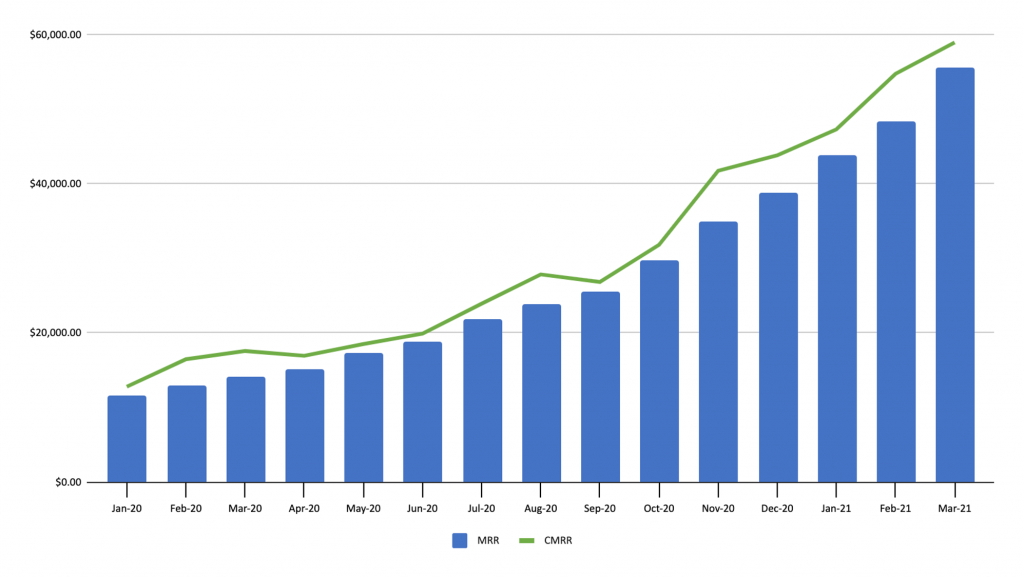
This type of graph gives you an up to date view of what’s happening with your sales and revenue retention + expansion efforts, so it is super helpful to include in your internal + board reporting.
You can find a google sheet with a worked example here: CMRR Example
FAQ
What do I do with [implementation revenue, one-off fees etc]?
Report them separately. In a SaaS company, it is mainly the MRR that makes your business more valuable. Collect the other revenue. Book it. Use it to cover burn. It’s valuable. Just don’t mix it into your MRR.
Frequently Asked Questions
What is the difference between MRR and CMRR?
MRR reflects the recurring revenue recognised from contracts being delivered. Committed MRR (CMRR) also counts signed new business and upsells that have not started yet, and removes churn and downgrades already communicated, so it shows the committed position earlier.
Why can MRR give a misleading picture of a SaaS business?
Because it lags reality. In the post's example, a December churn of 20% and December deals adding 40% only appear as a bad January and a 50% jump in February, reported a full three months after the deals were done.
How should SaaS companies treat one-off fees in recurring revenue metrics?
Report implementation revenue and one-off fees separately. They are valuable and can help cover burn, but it is mainly MRR that makes a SaaS business more valuable, so they should not be mixed in.