


SuperSeed's predictions for tech and venture in 2024: generative AI stays dominant despite copyright disputes, software sales rebound, M&A picks up, IPOs reopen in the second half, and venture shifts towards manufacturing and the real economy.
- SuperSeed expected 2024 to be another year of AI, with legal disputes over training data, such as The New York Times suing OpenAI, acting as speed bumps at most.
- Median EMCLOUD revenue growth had fallen from 35% to 18%, but Altimeter data showed ARR growth stabilising in Q3 2023, pointing to a software sales rebound.
- With inflation under control and rates likely to fall, SuperSeed expected more M&A in 2024, except for the largest deals facing regulatory scrutiny.
- A record IPO backlog led SuperSeed to expect IPO markets to reopen in the second half of 2024.
- Generative AI is creating new vertical application opportunities in the real economy, and manufacturing was the main focus of European B2B investors in 2023.
We’ve boldly forecasted the stock market and the next US president.
Now it’s time for a look at what will happen with tech and venture in the new year.
In 2024, (Generative) AI is still in the ascendancy…
2023 was the year of AI. This was kickstarted slightly early, when OpenAI launched ChatGPT on November 30th, 2022. As we said at the time, this changes everything.
We still think this is the case, as AI continues to be the main driver of everything in tech.
There are claims that 41% of all new computer code on Github now is AI-generated.
JP Morgan recently outlined their view on why this is very different from anything else we’ve seen in the past 20 years.
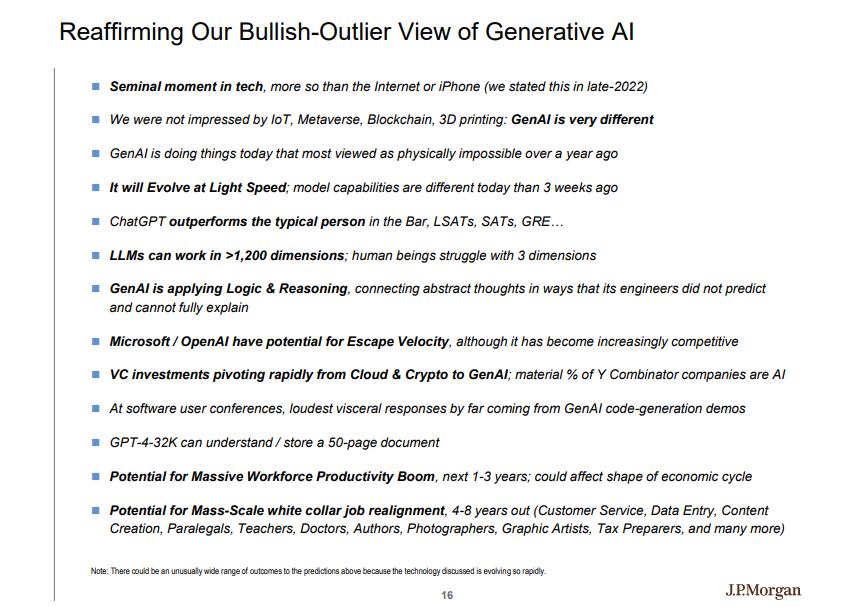
This is not just about making software developers more productive. It touches all parts of the economy.
And so PwC forecasts that AI will add $15trn to the global economy before the end of the decade.
Our expectation is that 2024 will continue to be yet another year of AI. We see so many smart founders build transformational SaaS platforms using this next-gen technology. On one hand, so much is alrady happening. On the other, we are still only getting started.
…but not without (legal) bumps in the road
The capabilities of the new generative AI models have indeed continued to blow us away in 2023. But they are learning all their skills from somewhere. And media companies have woken up to the fact that their IP has been one of the main inputs to the prowess of the new Gen AI models.
The New York Times has now sued OpenAI for copyright infringement.
Elsewhere, German median giant Axel Springer has a deal with OpenAI that enables the AI giant to use Axel Springer’s IP.
Expect many more legal bunfights around this going forward.
While this will impact the developers of the large foundational models, it will be speed bumps at most. The potential for the new models is so vast that these IP issues will be resolved – even if some of the resolution will linger into 2025.
We will see a rebound for software company sales in 2024
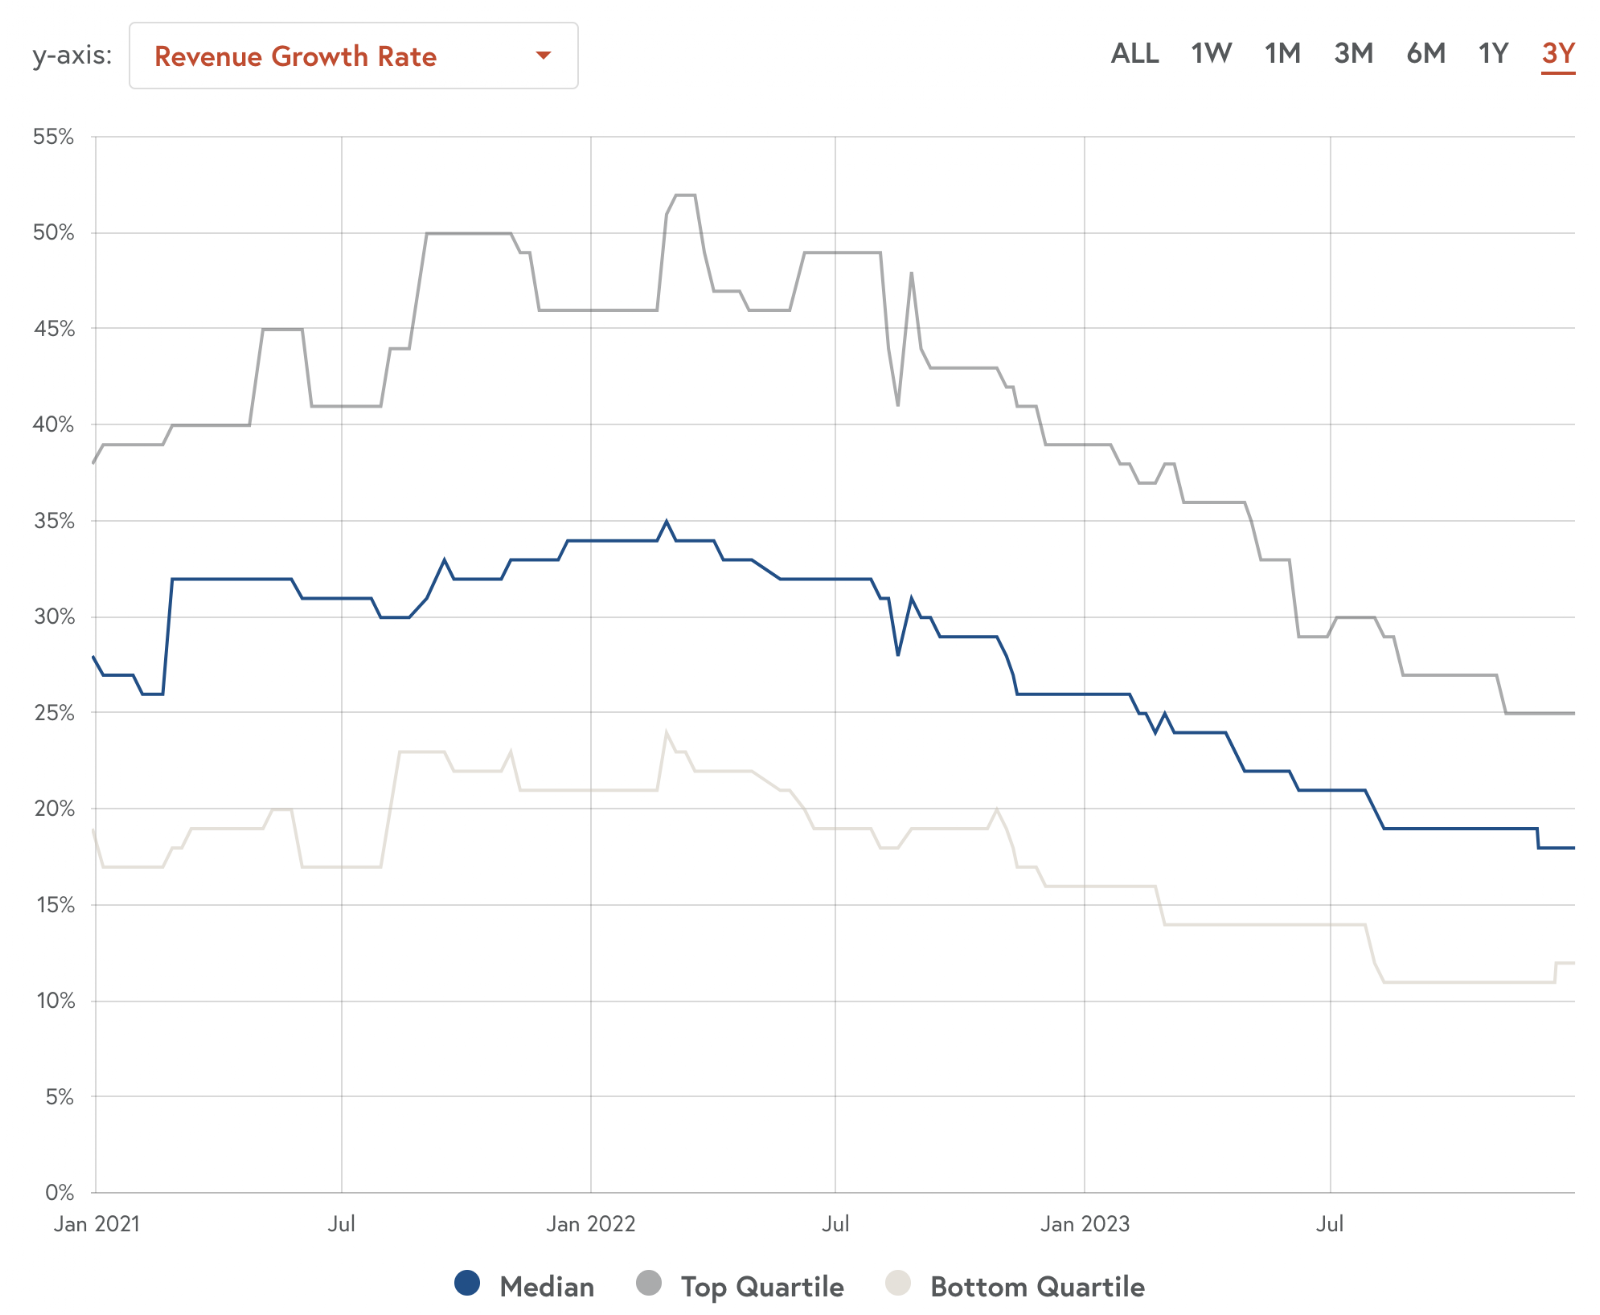
From the second half of 2022, businesses responded to economic uncertainty by trimming spend and consolidating vendors. This has led to a challenging climate for software companies, and the large public software vendors have reported shrinking growth rates. Note – they’ve still been growing – just more slowly than before. The median EMCLOUD revenue growth has shrunk from 35% to 18% per annum.
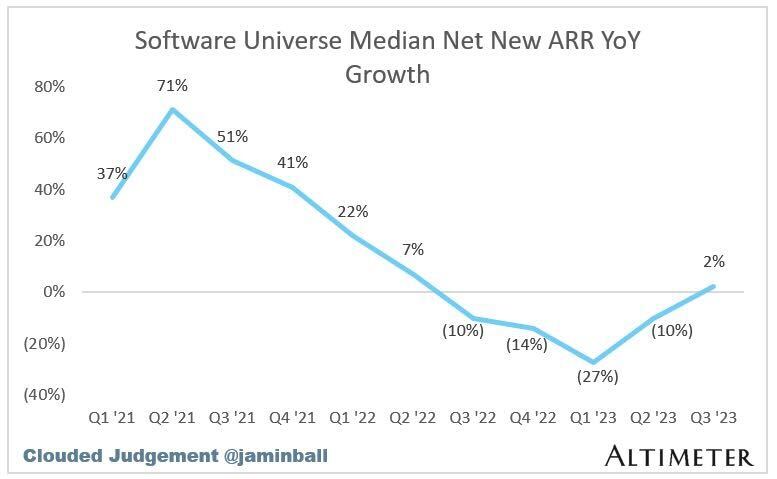
But it looks like this shrinkage is now turning. According to Altimeter, annual ARR growth rates stabilised in Q3 of 2023. And with declining inflation and interest rates expected to come down, we expect growth rates to generally stabilise and perhaps even increase in 2024.
We expect to see more M&A activity in 2024
While IPOs are often seen as the most attractive outcome for tech startups, M&A is the more common exit path. 2023 was a difficult year for exits, with deal value in Q1-Q3 down 41% on the same period in 2022.
Part of the challenges were driven by uncertainty around inflation and interest rates, plus the looming spectre of recession. Anti-trust regulation also played a role, with competition and markets authorities in the US and Europe probing several acquisitions. Microsoft’s $69 billion acquisition of Activision was ultimately approved, whereas Adobe’s proposed $20 billion purchase of Figma ultimately was called off due to regulatory action.
Barring major geopolitical destabilisation, we expect to see increased M&A in 2024. Inflation is under control, and interest rates are likely to come down. This provides corporates with greater certainty, and the lower rates make it easier to justify a price that will enable deals to be agreed. This should help everyone except for the very biggest multi-billion dollar acquisitions that might still be hampered by increased regulatory scrutiny.
We expect a reopening of IPO markets in the second half of 2024
2022 and 2023 have been slow years for IPOs, with fewer companies listing in 2023 than at any other point in the last decade.
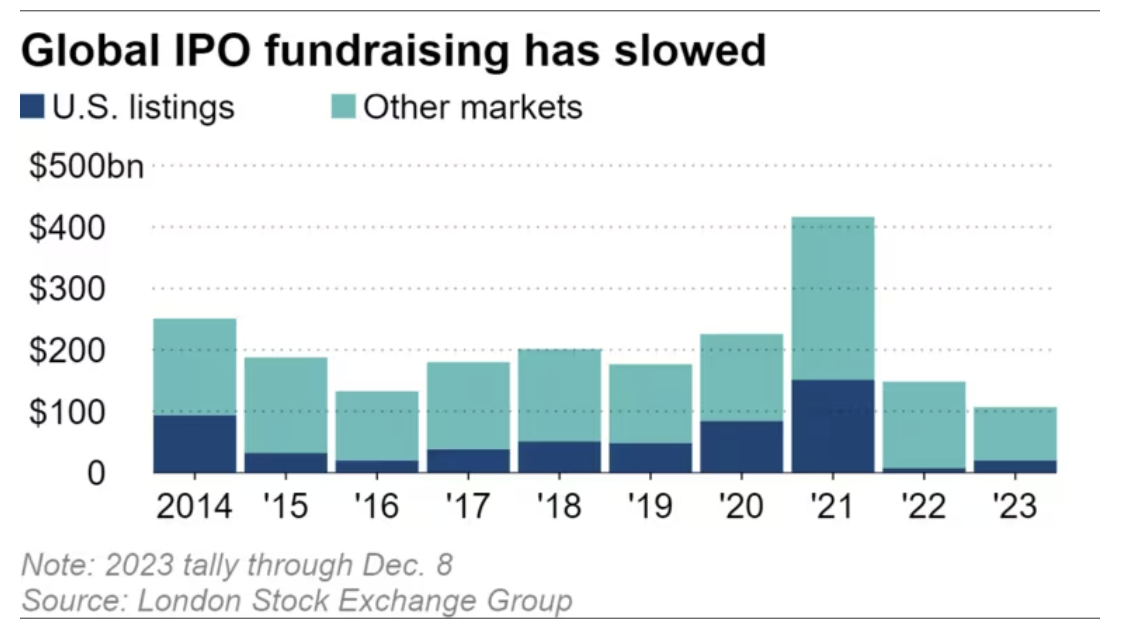
However, it is not for lack of quality companies waiting to go public. Goldman Sachs reports that there are plenty of companies lining up to IPO, with the backlog is as “high as it has ever been”.
This matches Pitchbook’s analysis of the IPO backlog.
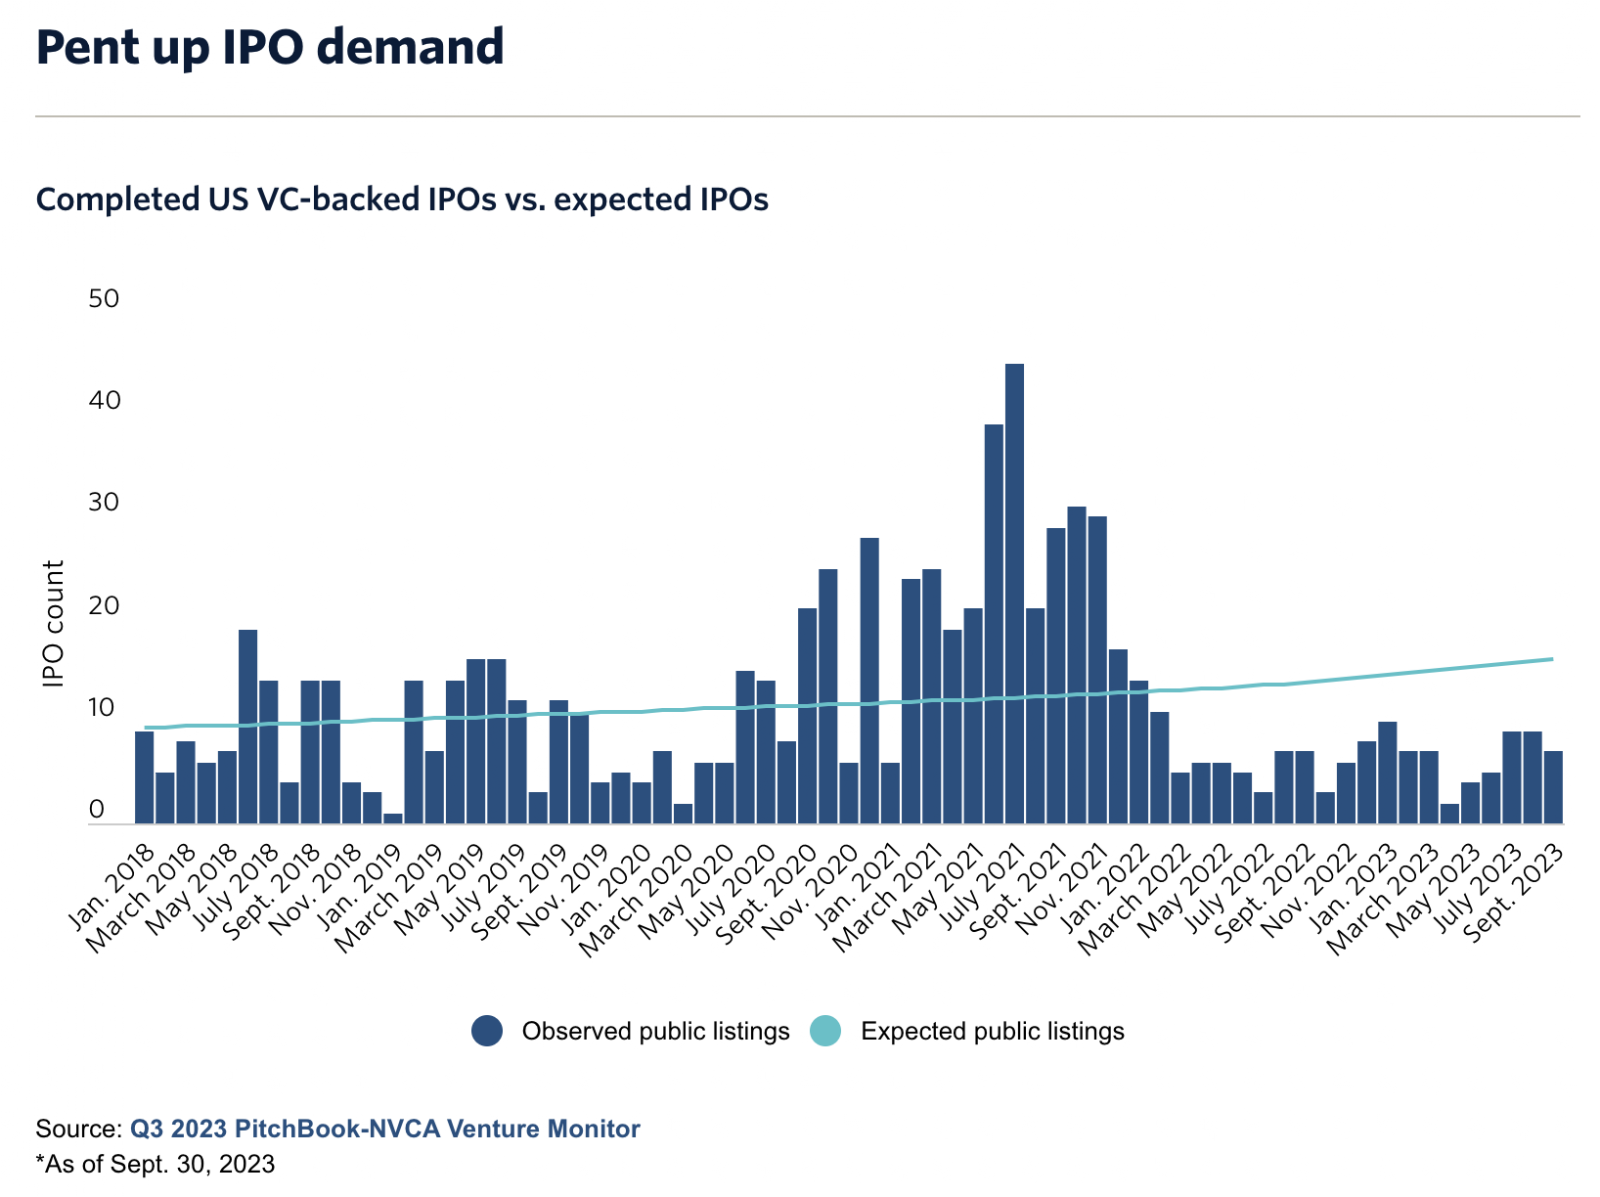
If the US economy stays on track and interest rates start to come down, we expect to see a better IPO environment in the second half of 2024.
VC Investing outlook
Generative AI reshuffles the playing field once again
Just like cloud computing ushered in SaaS as the new opportunity in enterprise software, so does generative AI give rise to a swathe of new opportunities in vertical applications. Because genAI models are so good at making sense of the real world, a lot of the opportunities will be in the real economy. Manufacturing, supply chain, healthcare, architecture and construction, agriculture, raw materials etc – all of these sectors will be impacted profoundly.
We see a continued shift to manufacturing and the real economy
Speaking of manufacturing, the shift is already underway. According to Dealroom, Manufacturing related investments were the main focus of European B2B investors in 2023.
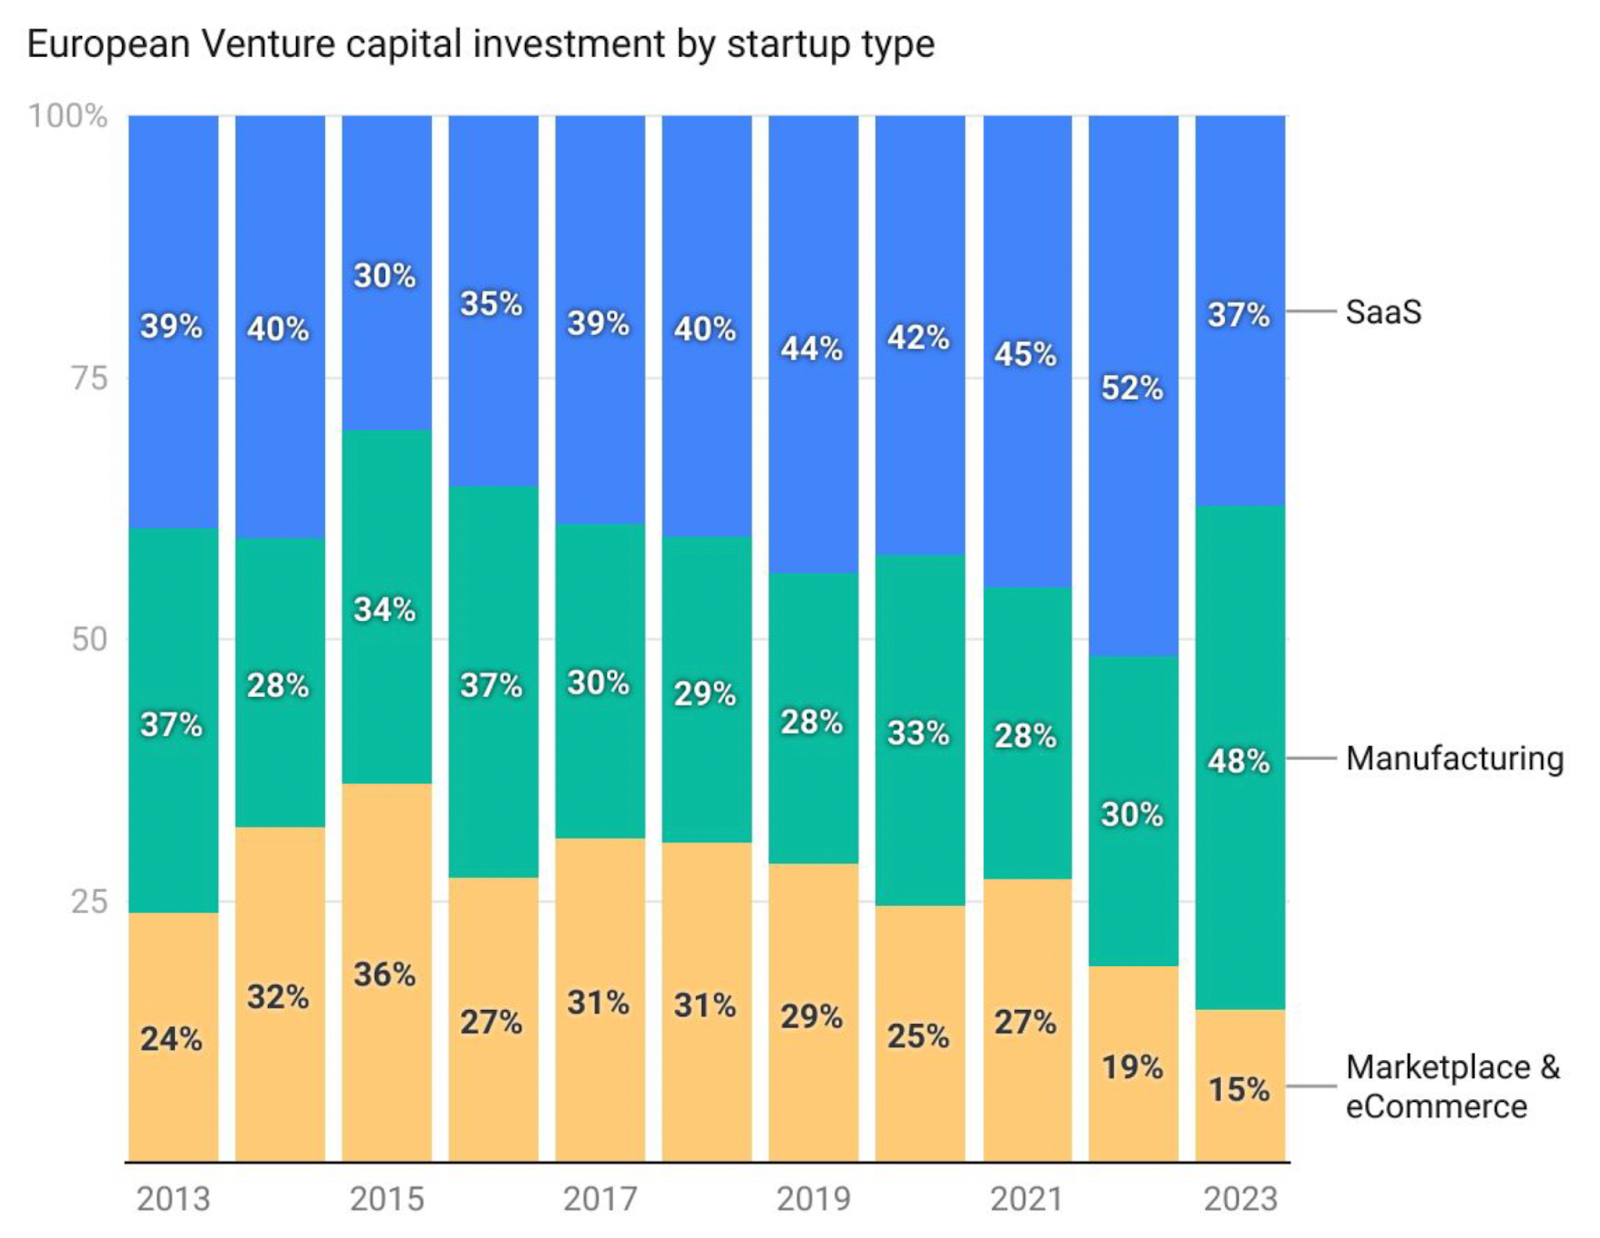
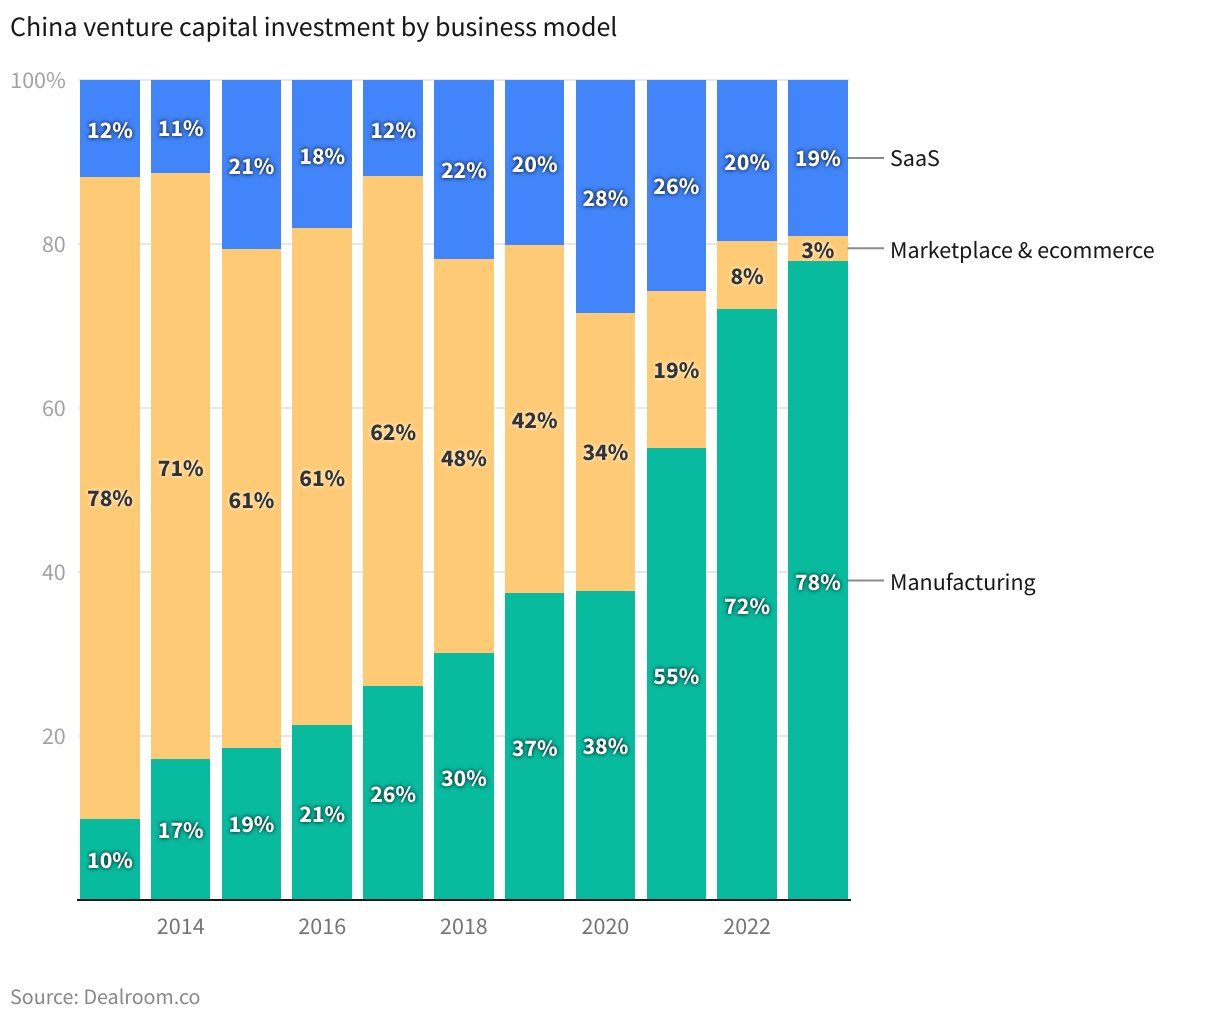
However, Europe is well behind China, where 78% of investments were manufacturing-related. While Chinese investors may be heading into a bubble, we still think there is plenty of scope for more investment that targets the real economy in Europe, and we see this as a hot space in 2024.
A little further out, it looks like we might finally be starting to crack the challenge of autonomous robotics. This is relevant in both manufacturing, mining and agriculture, where autonomous robots can help transform productivity.
2024 will be a strong year for productive venture capital
2022/2023 was challenging for many investors with exposure to VC. In all that noise, it’s easy to forget the good things that have been happening. In 2023, thousands of new companies were backed to solve the big challenges in business. As the AI revolution gains pace, we see this further accelerate in 2024.
Here is to a great year for founders that solve real problems to make us all more productive and prosperous.
Happy New Year!
Frequently Asked Questions
Why did SuperSeed expect more tech M&A in 2024?
Inflation was under control and interest rates were likely to come down, giving buyers more certainty and making prices easier to justify. Only the largest multi-billion dollar deals might still be held back by regulators.
Will copyright lawsuits stop generative AI?
SuperSeed thought not. It expected many more legal disputes, such as The New York Times suing OpenAI, but saw them as speed bumps that will be resolved because the potential of the models is so large.
Where did SuperSeed see the biggest venture opportunities for 2024?
In vertical applications built on generative AI, particularly in the real economy: manufacturing, supply chain, healthcare, architecture and construction, agriculture and raw materials. It also noted early progress on autonomous robotics.