


SuperSeed's August 2020 update reviews record GDP falls in the US and UK, the forces pulling the economy in different directions, why stock markets had recovered regardless, and why its early-stage tech thesis was unchanged, plus news on Intel, Apple and GPT-3.
- US Q2 2020 GDP fell 9.5% year on year, the largest drop on record, and UK GDP fell 21% from Q1, the worst in the G7.
- The post saw three competing forces: positive underlying trends, drag from unwinding stimulus and possible tax rises, and business failures still to come.
- UK insolvencies fell in Q2 2020 because of government support, but were expected to snap back as that support tapered.
- The S&P 500 was back at its all-time high, which the post linked to the strong prospects of the best-run companies, continued quantitative easing and rock-bottom interest rates.
- SuperSeed's startup thesis was unchanged: the most technologically sophisticated companies were doing best, and it still saw good early-stage opportunities for long-horizon investors.
Covid has left the global economy reeling. Despite the global turmoil, we’ve had an action-packed July with lots happening in the world of tech and venture.
First, let’s round up some of the macro trends.
US
Overall, the economic numbers for the past few months have been grim. US Q2 GDP was down 9.5% year-on-year – the largest drop on record.
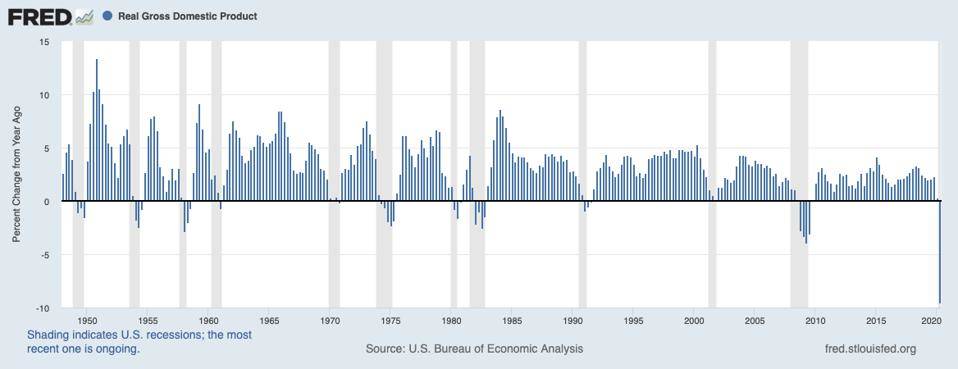
U.S BUREAU OF ECONOMIC ANALYSIS. FEDERAL RESERVE BANK OF ST. LOUIS
This took $2.1trn out of the economy, effectively erasing all growth over the past 5 years (the US economy was smaller in Q2 2020 than in Q1 2015).
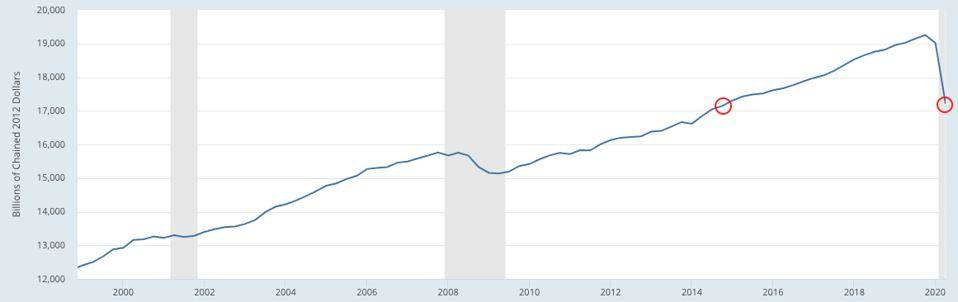
U.S. BUREAU OF ECONOMIC ANALYSIS, FEDERAL RESERVE BANK OF ST. LOUIS
We just haven’t seen anything like this in recent memory.
UK
UK GDP numbers are – if anything – looking worse. In Q2, GDP declined a whopping 21% from Q1, and the UK is in the unenviable position of having the worst performing economy in the G7.
The big picture
The US continues to be the economic locomotive of the global economy, and it’s clearly been hit badly by a combination of Covid and what looks like a lacking policy response from Washington.
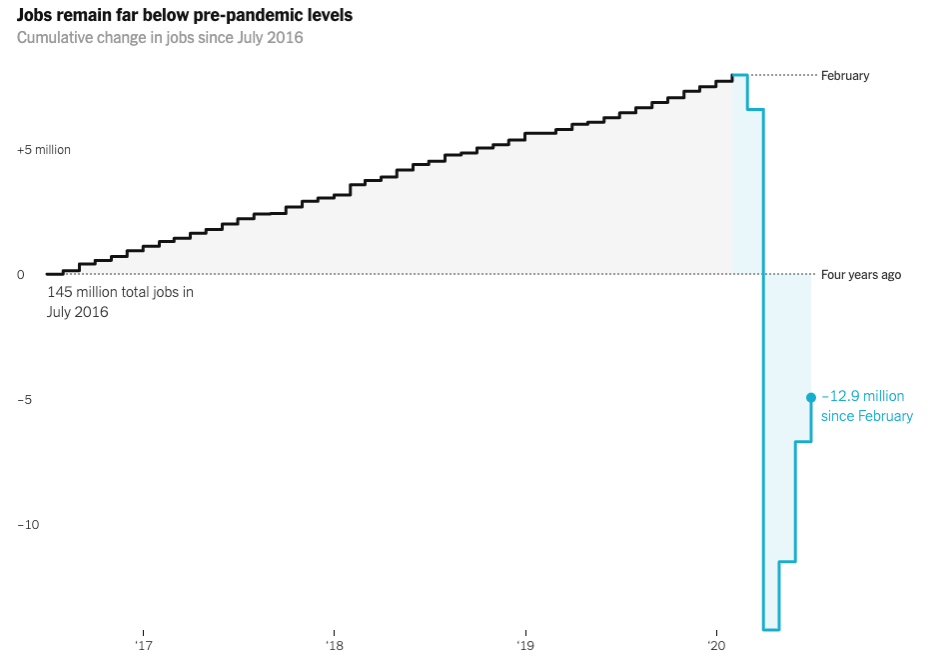
Although the US labour market has started recovering over the summer, jobs remain far below pre-pandemic levels.
But even so, it looks like the economy has started to heal; with that comes hopes that the worst is behind us, and that we can focus on rebuilding businesses and the wider economy.
But big questions remain as to how quickly we can get through this. Although governments have tried to cushion the impact to livelihoods and the economy by enacting substantial fiscal stimulus, this has come with a hit to the public finances not seen since the 2nd WW.
In terms of getting the economy back on track, there are multiple forces fighting each other:
- Positive underlying trends in the economy. Green shoots of the economy, such as we have seen from many companies (including our portfolio) reporting that business is picking up.
- Drag from unwinding stimulus and possible tax rises. Government stimulus starts to unwind as furlough payments are reduced and other stimulus measures pulled back. The Chancellor, Rishi Sunak is trying to soften the blow with his most recent stimulus package, and even the relatively upbeat Bank of England recently projected that unemployment will increase by 1 million to 2.5m by Christmas. And then of course there is a big bill which needs to be settled. Some analysts believe tax rises are likely, if not inevitable, and depending on how they are implemented, this could lead to a drag on the economy.
- The drag of business failures that are still to materialise. Perhaps surprisingly, the number of insolvencies in the UK fell in Q2 – just as we were at the peak of the pandemic. This was driven mainly by government measures which included extended credit from HMRC and the bounceback loans that were underwritten by the government, enabling otherwise struggling business to carry on trading. However, insolvencies are likely to snap back once the government support tapers away, making a ripple effect through the economy as one businesses failure means the loss of customers for other businesses, who in turn will struggle.
Whichever way you look at it, it seems like the economy will be quite bumpy in the next 6-12 months. Proceed with caution.
So, what does this mean for investing?
Investors who kept invested broadly in the stock-market throughout the crisis (e.g. through index trackers) have done well, with the SP500 now back at its all-time-high.
So is this a sign that things are better than they look, or just an indication that the stock market has formally decoupled from the economy?
Here is one possible interpretation:
- The long term prospects for the best run companies are still positive. If anything, Covid has improved the prospects for companies like Amazon, Microsoft and Google.
- Continued quantitative easing means that liquidity keeps flowing into the market.
- With interest rates at rock bottom, investors have fewer places to turn.
This doesn’t rule out the possibility that markets could get rocky again over the coming months – especially if the pandemic starts to spin out of control. But it does go a long way towards explaining their current heights.
From a startup investing perspective, our thesis is unchanged. The companies that are doing the best are those who are the most sophisticated with their technologies and business models. Tech continues to drive business transformation, and startups continue to contribute a lot of the underlying innovation – both in terms of tech but also in terms of business models. So if you have a long investment horizon, we continue to see what we believe are very good opportunities in early stage tech investing, also in the current market.
In other news
Intel loses the crown?
Intel recently announced a delay to their 7-nanometer transistor technology, meaning that they for the first time in decades don’t have the most sophisticated microprocessor manufacturing capability. This puts them behind Taiwanese TSMC, whose shares jumped $34bn on the day of Intel’s announcement. Intel had already had a knock, with Samsung overtaking the company as the largest semiconductor manufacturer in 2017. Although Intel regained the top spot last year, it looks like they have now fallen behind TSMC in terms of technological sophistication. As Apple is also looking to migrate away from Intel chips, it will be interesting to see what moves Intel will make to try to fight their way back to the top of the semiconductor industry.
Apple has a win in court
Apple had its €13bn Irish tax bill overturned. The European Commission had initially argued that Apple owed the additional tax on competition grounds. However, the EU’s general court overturned the ruling, saying that there was insufficient evidence that the Irish tax breaks were anti-competitive. The ruling is likely to be appealed to the European Court of Justice.
GPT-3 – major news in AI
And in exciting AI news, the GPT-3 is an exciting new algorithm from OpenAI that shows the promise of what AI can achieve. The algorithm has the ability to construct not just sentences, but write whole documents, poetry, computer code or answering medical questions. Although the results are impressive, there are still quite a few issues with the algorithm, and it does’t look like it is about to put us all out of a job just yet.
That’s it for this month. Not quite a quiet summer, but quite possibly a prelude of what’s to come in the months ahead.
This article is published by SuperSeed Ventures LLP which is authorised and regulated by the Financial Conduct Authority. The article does not constitute substantive research or analysis, and should not be construed as an investment recommendation in relation to any publicly traded company. Please note, investments in unlisted early stage companies are illiquid and expose investors to a significant risk of losing all money invested. Please always seek independent financial advice before making investment decisions.
Frequently Asked Questions
Why had the stock market recovered while the economy was so weak in mid-2020?
The post offered one interpretation: Covid had if anything improved the prospects of companies like Amazon, Microsoft and Google, quantitative easing kept liquidity flowing, and with interest rates at rock bottom investors had few other places to turn.
Why did UK insolvencies fall during the pandemic?
Government measures, including extended credit from HMRC and government-backed bounceback loans, allowed struggling businesses to keep trading. The post expected insolvencies to rise once that support was withdrawn.
Did Covid change SuperSeed's investment thesis?
No. SuperSeed said the companies doing best were those most sophisticated in technology and business models, and that it continued to see very good opportunities in early-stage tech for investors with a long horizon.