


SuperSeed's August 2021 update looks at how a strong IPO market was recycling liquidity into venture capital, and weighs the risk that returning inflation would force interest rate rises, drawing on Paul Krugman's reasons for thinking the fears may be overblown.
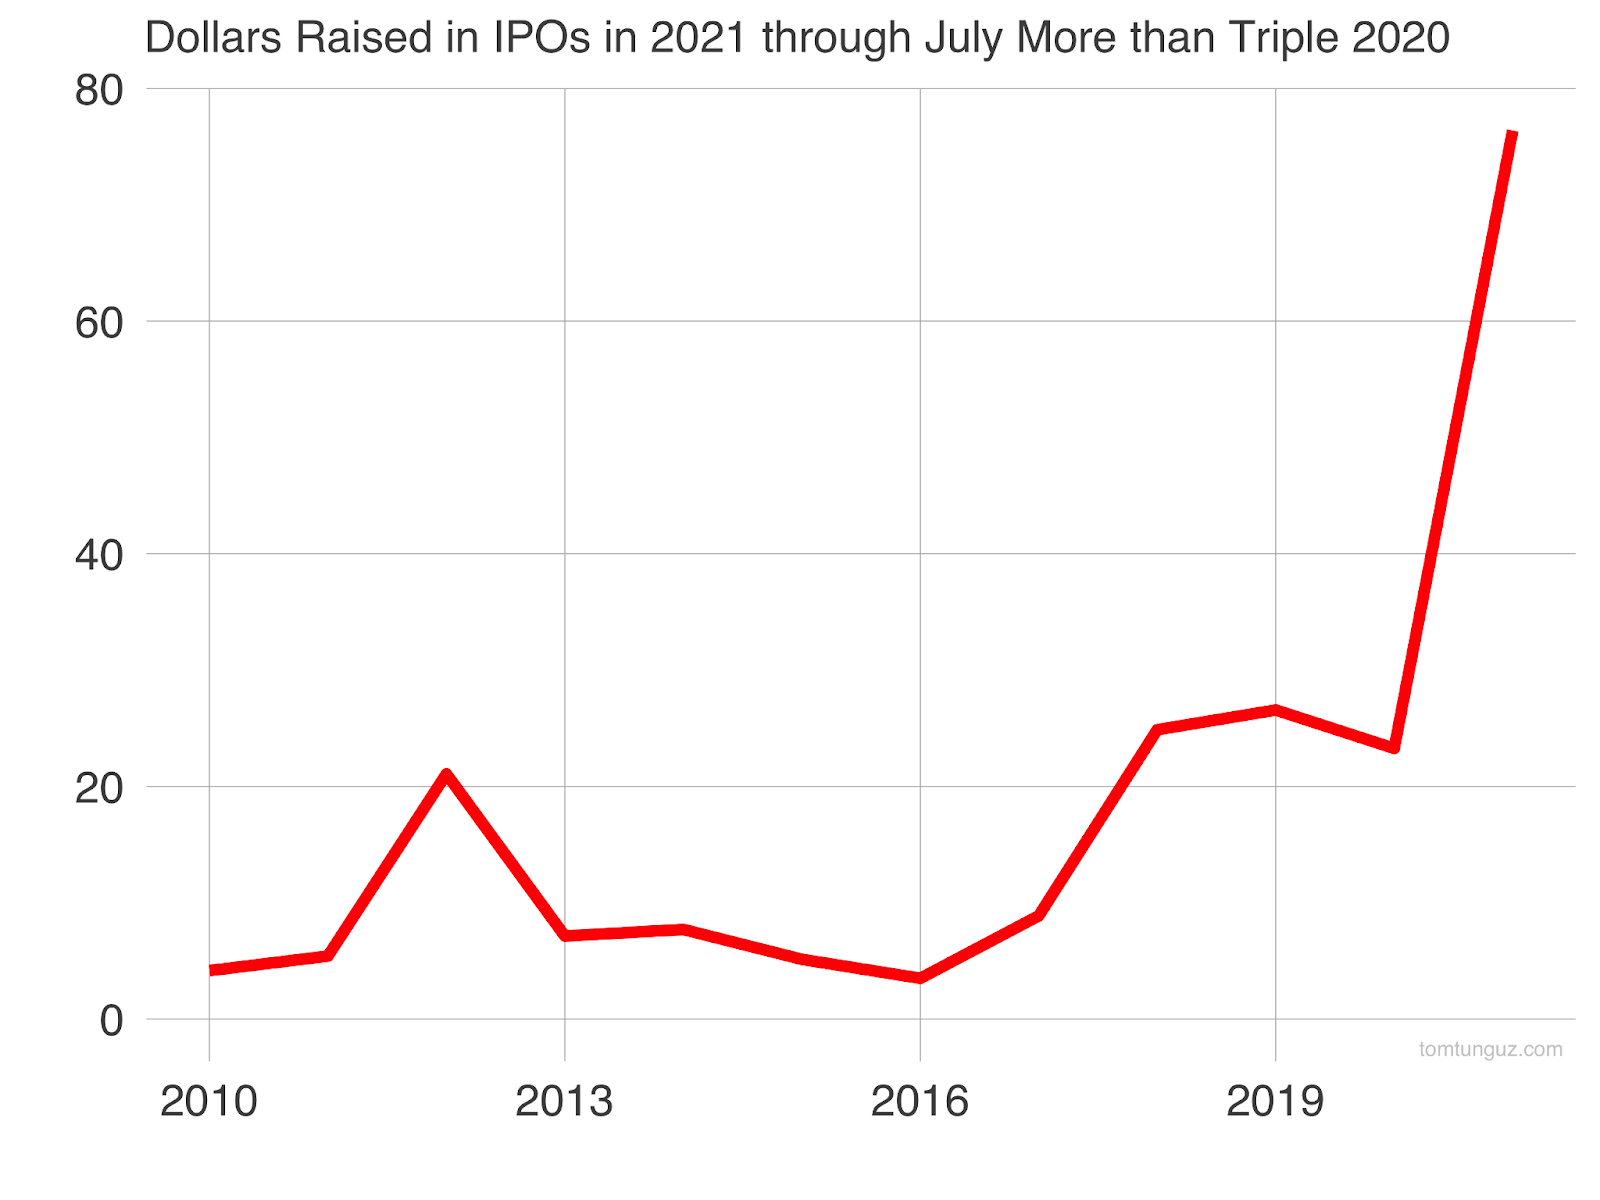
- In the first half of 2021, US IPO proceeds were more than triple the whole of 2020, and much of that money flows back into venture as distributions and new investment.
- In 2015, VC-backed companies accounted for 44% of the R&D spend of all US public companies.
- US core CPI rose 4.5% year on year in June 2021, the largest increase since November 1991.
- Higher inflation could force rate rises that slow earnings growth and raise the discount rate used to value companies.
- Paul Krugman argued the spike was driven partly by semiconductor shortages pushing up car prices, and that pent-up demand for perishable services would not all be spent at once.
We are now well into the summer period, and this month we look at liquidity in venture capital and the threat of a return of inflation.
Liquidity in venture capital
Last month we examined how H1 of 2021 has been a record year for the amount invested in venture capital. A significant portion of this investment was in mega growth rounds (+$250m) that have set records. From our perspective, it is positive to see so much capital allocated to grow tech companies at the later stages. One of the critical drivers for this growth is the success of the IPO market. Although there have been initial disappointments like the Deliveroo IPO in April, that stock has since recovered (up over 17% since April 1st). And many others (like Darktrace) have done phenomenally well post IPO.
Half a decade ago, there was a dearth of IPOs, which meant that it took longer for VC investors to turn profits into cash. This situation has now been turned entirely on its head. In the first half of 2021, the amount of dollars raised through IPOs in the US was more than triple all of 2020. Some of this is driven by SPACs, and there are reasonable criticisms of the recent SPAC surge. However, a large part of the IPO proceeds is ultimately finding its way back into the venture eco-system – first as distributions to investors and then as investments into the next wave of early startups.
In 2015, VC backed companies accounted for 44% of the R&D spend of all US public companies – a number that’s likely only gone up since then. Therefore, we see the IPO liquidity flowing through the startup ecosystem as positive – both for investors and the wider economy.
Is inflation coming back?
For the past 30 years, we have lived in a blissful world of declining inflation, with OECD averages down from ~10% p.a. in the 80s to ~2% in the noughties (FT Paywall)
However, this year, the spectre of inflation has been rearing its head again, with the US Core Consumer Price Index (CPI) up 4.5% year-over-year in June. This is the largest increase in the CPI since November 1991, and it has rightly gotten many observers concerned that inflation is on the march.
Why should we care?
Besides the obvious (rising prices and erosion of purchasing power), increasing inflation might force central bankers to raise interest rates. This could have a double whammy effect. It could:
- put a damper on economic activity, which would slow earnings growth, and
- mean that a higher rate of interest should be used when discounting expected future cash flows (still the primary way to value public companies). In other words – not a promising scenario.
But is there a likelihood that the inflation fears are overblown?
The Nobel Prize-winning economist Paul Krugman recently analysed this issue, and he suggested two major reasons for why inflation might not be as threatening as some think:
- A large part of the increase in CPI has been driven by the increasing price of cars, which, in turn, was caused by shortages in the supply chain – primarily from semiconductors (yes – cars are really driving computers nowadays – Marc Andreessen was not wrong). TSMC, which is one of the largest suppliers of chips to the automotive industry, said in mid-July that they would ramp production by 60% this year. As these types of supply chain bottlenecks get cleared up, that will help take the pressure off inflation.
- Although consumption was down in 2020 (and with it – GDP), most of the slump was in perishable goods and services (vacations, restaurant visits, haircuts). In contrast, investment in durable goods like TV’s and refrigerators held up just fine. So although savings rates were up and there theoretically is a lot of money ready to be spent (which could cause inflation), it is unlikely that we will all suddenly go have a year’s worth of haircuts or restaurant meals all at once. There is just a limit to how many of those perishable goods we can consume – even if we have been deprived for too long.
So what does this mean for UK interest rates? According to the Bank of England, it doesn’t look like rate increases are imminent (FT: paywall). But it’s certainly worth continuing to keep an eye on inflation as we enter the next phase of the post-covid recovery.
Frequently Asked Questions
Why does a strong IPO market matter for venture capital?
IPOs let VC investors turn gains into cash. The post explains that much of the IPO proceeds returns to the venture ecosystem, first as distributions to investors and then as investment in the next wave of startups.
Why should investors care about rising inflation?
Beyond eroding purchasing power, inflation might force central banks to raise interest rates, which could slow economic activity and earnings and increase the rate used to discount future cash flows when valuing companies.
Why might the 2021 inflation fears have been overblown?
Paul Krugman pointed to temporary supply bottlenecks, such as semiconductor shortages raising car prices, and noted that the 2020 slump was mostly in perishable services like restaurant meals and haircuts, which people will not suddenly catch up on all at once.